 By MyJobAlly
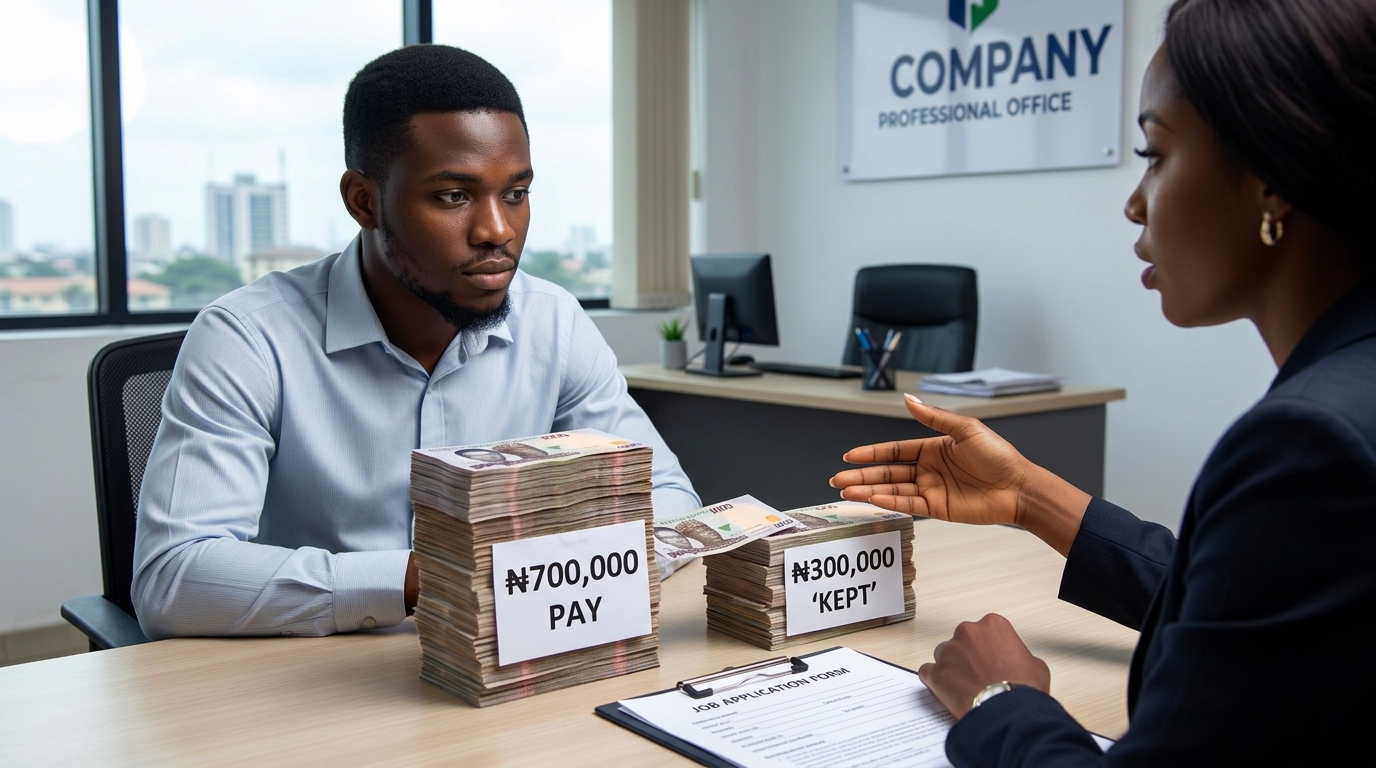
A note on the figures: The skit that inspired this article uses a ₦100,000 monthly package, split into ₦70,000 paid in cash and ₦30,000 held back. The headline scales those numbers up tenfold to ₦1,000,000, ₦700,000, and ₦300,000 so the ratio is easy to see: 70 percent paid to you now, and 30 percent held until you leave. The ratio is what matters. The worked examples in this article use the original ₦70,000 and ₦30,000 figures, so if your own package is larger or smaller, multiply or divide to match. A ₦1,000,000 monthly package is also not a typical Nigerian salary, and no real job is being advertised here.
A boss promises to "save" part of your pay and hand it over when you leave, but only if you give two months' notice. Is that clever protection for a small business or a trap for employees? Here is what Nigerian law and the research say, and what to ask before you sign.
Credit: This article was inspired by a LinkedIn post by Joseph Ogundare, which features a short roleplay about an employer's unconventional retention system (original post). The scenario below is paraphrased from the dialogue shared with us. The legal context, data, and advice are our own additions.
Let's start with the scene. A business owner has ₦100,000 a month to spend on a new hire. Instead of paying all of it as salary, she pays ₦70,000 in cash and sets aside ₦30,000 a month in a company "savings" pot. The employee can collect the whole pot when they leave, provided they give two months' notice and complete a proper handover. If they leave without that notice, they lose the savings. When her HR manager asks why, the owner explains that staff sometimes collect salary and vanish the next day, leaving a small business scrambling. She says she is not trying to stop anyone from resigning. She wants a reason for people to leave properly.
The candidate in the skit says, "I'm interested." Should you be? The honest answer is: it depends on what that ₦30,000 legally is, who holds it, and what is written down. This article walks through both sides, tests the idea against Nigerian law, and gives you a checklist for any job offer that contains a "retention" or "savings" feature. Many of the statistics on quitting come from the United States and other markets, so treat them as benchmarks rather than Nigerian forecasts.
First, Why Employers Come Up With Systems Like This
The owner's frustration is real, and it helps to understand it before judging the design.
Surveys show that abrupt exits are not rare. An iHire survey of US workers found that 21.6 percent had quit a job without giving notice, including 19.2 percent of Gen Z workers (iHire, via SHRM Vendor Directory). A Monster survey reported by CPA Practice Advisor found that 47 percent of US workers say they have abruptly quit without notice, often as a protest against poor treatment or a toxic environment, and that 87 percent believe such exits are justified when conditions are poor (CPA Practice Advisor, reporting Monster's 2025 Revenge Quitting Report). Note that Monster and iHire are job platforms, and neither survey is Nigerian.
For a large company, a sudden resignation is an inconvenience. For a five-person business, it can mean a missed client deadline or a shop that can't open. That is why many small employers introduce long notice periods, guarantors, or deferred pay. The two-month handover in the skit is a reasonable ask in itself. The debate is about the penalty attached to it.
The Core Question: Is the ₦30,000 Salary or a Bonus?
Everything turns on this. If the ₦30,000 is part of the pay you have earned for work already done, taking it away looks very different from withholding a bonus that you only earn by meeting a condition.
Start with what the Labour Act says about wages. Its wage-protection provisions limit when an employer can deduct from wages, and its termination section sets minimum notice periods, which increase with length of service: one day for three months or less, one week for up to two years, two weeks for two to five years, and one month for five years or more (Techpoint Africa; Labour Act text). A two-month notice period goes beyond those minimums, but Nigerian courts have enforced longer notice periods that are written into a contract. In one National Industrial Court case, an employee gave four weeks' notice under a contract that required three months. The court held her notice ineffectual and treated her as having resigned without notice, but the remedy was one month's salary in lieu of notice, not the loss of everything she was owed (National Industrial Court of Nigeria).
Courts have also separated salary from benefits. A legal commentary on another National Industrial Court decision explains that where a contract requires a set notice period or pay in lieu, an employee who walks out may forfeit claimable benefits, and that an employer may withhold fringe benefits such as bonuses and allowances that depend on fulfilling the contract (Mondaq, "I Resign With Immediate Effect"). Read the full commentary, because it distinguishes what counts as a benefit from earned pay.
The flip side came in a February 2025 ruling. The National Industrial Court held that an employer could not withhold an employee's salary for missing KPIs, because the contract did not make her salary depend on them, and commentators concluded that any portion of pay tied to conditions must be set out explicitly in the contract. The same ruling also confirmed that an employee's duty to give contractual notice continues even when the employer owes unpaid salary, and that an employee can't shorten the notice period unilaterally (Mondaq, Olayanju v Global Mercantile and Corporate Logistics Ltd).
What this means in plain terms. A forfeiture clause is more likely to be enforceable when it is a clearly written, conditional retention benefit in a signed contract. It looks shakier when the same money is described as part of your salary, or when the terms were only spoken. These are general observations from published commentary, not a ruling on any particular contract. The Labour Act also covers mainly manual and clerical workers (LawPadi), so many professionals depend even more on what their contract says. Get a lawyer to read yours if the sums are significant.
What the ₦30,000 Really Costs You
Let's do the arithmetic the skit skips. At ₦30,000 a month, the pot grows to ₦360,000 after 12 months, ₦720,000 after 24 months, and about ₦1.08 million after three years. That looks generous. Now consider the costs.
You can't spend it. Your cash pay is ₦70,000, not ₦100,000. Rent, transport, and food are paid from the ₦70,000. Note that ₦70,000 equals the national minimum wage, which applies to employers with 25 or more employees, while smaller establishments are exempt (Mondaq). Whether a withheld portion could ever count towards minimum wage compliance is a question for a lawyer. What is clear is the size of the cash gap: for a low earner, ₦70,000 in hand may not stretch as far as ₦100,000 on paper.
Inflation eats idle savings. Headline inflation was 15.39 percent in August 2026 (Nairametrics). At that rate, money sitting for a year buys about 13 percent less unless it earns a return. Ask whether the pot earns anything.
You carry the risk of the employer's health. Money held by a small company is, in practice, only as safe as the company. If the business struggles or closes, savings that exist only on a ledger may be hard to recover. Contrast this with pension contributions: once an employer remits them to a pension fund administrator, the employer can no longer access them (BusinessDay). That protection is exactly what a company-held pot lacks. This is a reasoned risk, not a prediction about any employer.
It doesn't replace your pension. Under the Pension Reform Act 2014, employers must contribute at least 10 percent and employees at least 8 percent of monthly emoluments, defined as at least basic salary, housing, and transport, and employers with three or more employees must enrol staff (ThisDay, citing PenCom guidance; BusinessDay). If an employer reduces your "salary" to fund a savings pot, check that your pension and other statutory benefits are still calculated correctly.
There may be tax questions. Ask how the payout will be treated. If you get a lump sum on exit, you want to know in advance whether tax applies and who will handle it.
Is It Fair? The Case For and Against
The case for. The scheme gives reluctant savers a forced lump sum. It rewards people who stay and leave properly. It protects a small employer from sudden gaps, and it can be honest if explained clearly. Some employees would welcome it, especially if the savings are matched, safely held, and accessible in real emergencies.
The case against. The design is lopsided as described in the skit. The employee loses the pot for leaving without two months' notice, but nothing in the dialogue says what happens if the employer ends the job suddenly, delays salary, or the workplace turns abusive. "No negotiation" and "two months, no exceptions" leave no room for illness, a family emergency, or harassment. Money tied to staying also makes it harder to walk away from a bad situation, which matters in light of what we know about Gen Z and workplace expectations and the many workers who leave jobs because of mistreatment.
The fairest reading is that the idea of a notice incentive is legitimate, while the details decide whether it is a benefit or a trap.
Questions to Ask Before You Accept
- Is the ₦30,000 part of my salary, or a separate benefit? Ask for the exact wording in the contract.
- Is it in writing, signed by both of us? A spoken promise is hard to prove.
- Who holds the money, and where? A separate account, a pension fund, or the company's general funds?
- What happens if the company closes or can't pay?
- What happens if you end my job, or fail to pay my salary on time? Do I still lose the pot?
- Is notice reciprocal? Will I get two months' notice if you let me go?
- Are there exceptions for illness, family emergencies, harassment, or unpaid wages?
- Does the pot earn anything, and how is it taxed on payout?
- How is my pension handled, and is it calculated on my full package?
- Can I see a worked example of what I would receive after 12, 24, and 36 months?
A Realistic Sequence
- Read the whole offer, not just the headline figure. Look for the notice clause, the forfeiture wording, and how pay is split.
- Compare in cash terms. Judge the job on what lands in your account each month, and treat the savings as a separate, conditional extra. See our guide to equity compensation for small business employers for how to think about pay you can't touch yet.
- Benchmark the market. Check what similar roles pay in cash. Published ranges help, as we explain in salary transparency laws and what employers need to know.
- Ask for changes in writing. Reasonable asks include reciprocal notice, emergency exceptions, a protected account, and a vesting schedule where you receive part of the savings each year.
- Get advice on large sums. If the pot could reach seven figures, a short consultation with an employment lawyer is cheap insurance.
- Decide on total value. If the cash pay covers your needs, the terms are clear and fair, and the money is safe, the scheme can work for you. If any of those fail, treat it as a risk, not a bonus.
- If you accept, leave well. Whatever the contract says, a proper notice and handover protects your reference, your reputation, and your savings.
What Not to Do
Don't sign on a spoken promise. If the pot matters to you, it belongs in a signed document. Don't count the savings as spendable pay when comparing offers or planning your budget. Don't ghost. Even if the system feels unfair, vanishing damages your reference and may expose you to a claim, as the notice cases show. Don't assume "no negotiation" means no negotiation. Many conditions are open to discussion before you sign, not after. Don't pay anyone to get a job. A genuine employer never charges you to hire you.
The Bottom Line
The skit captures a real tension. Small employers need notice and proper handovers, and employees need pay they can use and protections they can trust. A scheme that ties part of your pay to a fair, clearly written, reciprocal notice rule can be a reasonable deal. One that quietly withholds earned pay, gives you no safeguards, and leaves the money in an unprotected pot is closer to a trap. The word "savings" doesn't decide which it is. The contract does. Read it, question it, and get it in writing before you say "I'm interested."
This article was inspired by a LinkedIn post by Joseph Ogundare and draws on the Labour Act, National Industrial Court of Nigeria decisions and commentary, the Pension Reform Act 2014, National Minimum Wage legislation, iHire, Monster, and Nigerian inflation data, current as of October 2026. Most survey data comes from the United States and is used as a benchmark only. Legal commentary is general information, not legal advice, and outcomes depend on the exact wording of your contract and the facts of your case. Consult a qualified employment lawyer before signing or disputing any contract.